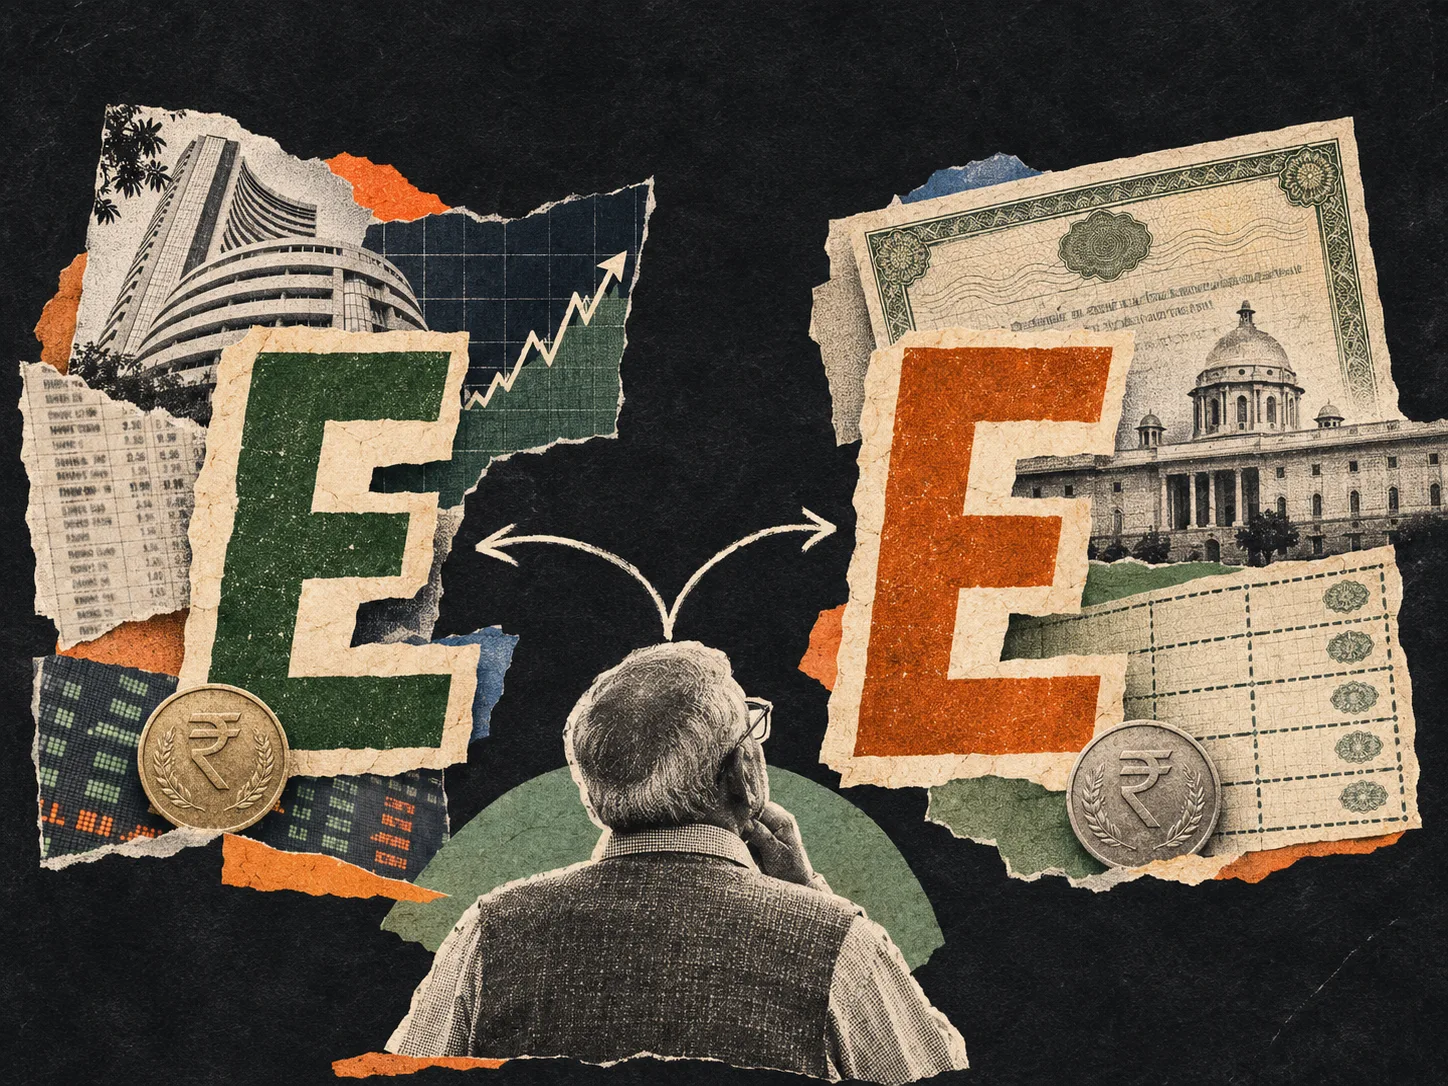
NPS now has two Es: one for equity, one for debt
NPS now sorts pension fund schemes into five categories, A to E, by how much they hold in shares. Category E holds the least. By 1 December, the letters come off the scheme names.
PFRDA's circular of 28 August 2026 puts every NPS scheme a pension fund launches under its own name into one of five categories, A (80% to 100% in equity) down to E (up to 10%). In Active Choice, E still stands for the equity asset class. A 2 November amendment takes the category letter out of scheme names, and every platform must follow the new rules by 1 December 2026.
Was this forwarded to you? Sign up to get Compound in your inbox.
For most NPS subscribers, E has meant one thing for years. It is the equity asset class, next to C for corporate bonds and G for government securities.
On 28 August 2026, PFRDA, the pension regulator, gave the letters A to E a second meaning. They became the codes for five categories of pension fund schemes. In that list, E is the debt category, with at most 10% in shares.
The first circular put the letter in each scheme's name. A circular of 2 November takes it out again. Both must be in place across NPS by 1 December 2026.
Two kinds of NPS choice
The August circular sorts all NPS investment options into five types. Two of them are for subscribers who choose how their money is invested.
- Active Choice. You split your money across the asset classes E, C and G. Equity is capped at 75% in Tier I, the pension account. Tier II, the voluntary account, allows up to 100%.
- MSF schemes. MSF stands for the Multiple Scheme Framework. These are ready-made schemes that a pension fund designs and PFRDA approves. You pick one scheme and the pension fund runs the mix.
The other three types are:
- lifecycle schemes, which cut equity as you age
- NPS Sanchay, for the informal sector
- themed schemes such as NPS Vatsalya
Same letter, opposite ends
Every MSF scheme now has to sit in one category, set by how much it may hold in equity.
| Category | Name in the circular | Equity it may hold |
|---|---|---|
| A | Aggressive Growth, Very High Risk | 80% to 100% |
| B | High Growth, High Risk | 60% to 80% |
| C | Balanced Growth, Medium Risk | 35% to 60% |
| D | Conservative | 10% to 35% |
| E | Debt (government and corporate bonds) | 0% to 10% |
So C and E now have two meanings in NPS. In Active Choice, C is corporate bonds and E is equity. As MSF categories, C is a balanced scheme and E is a debt scheme.
What the categories mean for ₹40 lakh
Illustration. Take a Tier I balance of ₹40 lakh. The rules set these limits on how much of it can be in shares.
| Where the ₹40 lakh sits | Most it can hold in equity |
|---|---|
| Active Choice | ₹30 lakh (75%) |
| Category A scheme | ₹40 lakh (100%) |
| Category C scheme | ₹24 lakh (60%) |
| Category E scheme | ₹4 lakh (10%) |
A Category A scheme also has a floor. It must hold at least 80% in equity, which is ₹32 lakh here.
The letter comes off the name
The August circular wanted names like "XYZ NPS A Retirement Scheme". Pension funds had 30 days to rename and restructure their MSF schemes to fit one category each.
The 2 November amendment drops the letter. A scheme name is now the pension fund's short name, "NPS" and a name the fund chooses. Tier II schemes add "Tier II" at the end.
The category moves to a line of its own. Ads, brochures and the scheme's essentials document must print the full category, such as "Aggressive Growth – Very High Risk", next to or below the name.
PFRDA's stated reason is to keep the risk category visible without making the name long and hard to recall.
Who shows you what
The amendment also sets what each screen must show once you pick a category.
- NPS Central and the CRA platforms, the record-keepers' sites, show every pension fund's schemes in that category.
- A point of presence's own platform, such as a bank or broker that sells NPS, also shows every fund. It may put one pension fund on top and pre-select a scheme.
- A pension fund's own website or app may show only that fund's schemes, when you chose to go there.
Before you pick a fund, the screen must show each scheme's launch date, past returns against its benchmark, charges, riskometer and assets under management.
Limits that come with switching
- You can make two change requests a financial year for each account. A request can change the pension fund, the scheme or both.
- Lifecycle and Active Choice are one or the other in a PRAN, the NPS account number. You can hold several MSF schemes at once.
- Changing scheme keeps the vesting period counted from the day the account opened.
- Merging one scheme into another works differently. The merged money takes on the target scheme's vesting period, withdrawal limits and charges.
Accounts opened through an employer can change schemes only as far as PFRDA's circular of 7 November 2025 allows.
The same charges apply across these types. The circular lists pension fund and point of presence charges of 0.24% to 0.32% a year for subscribers who join through a point of presence. Direct subscribers pay 0.04% to 0.12%. CRA fees, a small trust fee and GST come on top.
What isn't settled yet
- The new names. Each pension fund picks its own scheme names, and the amendment's deadline is 1 December.
- Government accounts. The framework does not apply to accounts of government employees.
- Tax. The circulars do not change tax, and this piece does not cover it.
We post the charts behind these pieces on X (@revaprivate) and LinkedIn, and every new piece on our WhatsApp channel. Follow along to get them first.
Questions
- What are the new NPS scheme categories A to E?
- Under PFRDA's circular of 28 August 2026, every MSF scheme sits in one category by its equity limit: A holds 80% to 100% in equity, B 60% to 80%, C 35% to 60%, D 10% to 35% and E up to 10%.
- Is NPS Scheme E still equity?
- In Active Choice, E is still the equity asset class, capped at 75% in Tier I. As an MSF category, E is the debt category, with at most 10% in equity.
- Will the category letter appear in NPS scheme names?
- No. PFRDA's amendment of 2 November 2026 says the category code shall not form part of the scheme name. The full category must be printed next to or below the name instead.
- When do the new NPS scheme rules apply?
- PFRDA's 2 November 2026 circular asks pension funds, points of presence and CRAs to make the changes to names, documents, websites, apps and onboarding by 1 December 2026.
- How many times can I change my NPS scheme in a year?
- Two change requests a financial year for each account, counting a change of pension fund, scheme or both as one request, under the 28 August 2026 circular.
- Can an NPS scheme hold more than 75% in equity?
- Active Choice is capped at 75% equity in Tier I. A Category A MSF scheme must hold 80% to 100% in equity.
Sources
- PFRDA circular PFRDA/2026/47/REG-PF/10, Standardised framework for classification and presentation of schemes under the NPS (28 Aug 2026)
- PFRDA circular PFRDA/2026/48/REG-PF/11, Operationalising the framework for classification and presentation of schemes under the NPS (28 Aug 2026)
- PFRDA circular PFRDA/2026/52/REG-PF/12, Amendment to the circular on the standardised framework (2 Nov 2026)
Compound is analysis, not investment advice. Reva Money is not a SEBI-registered investment adviser.